France Buried Under a $4 Trillion Debt Mountain
Soaring borrowing costs, rising pension and defense spending push Europe’s second-largest economy deeper into fiscal trouble
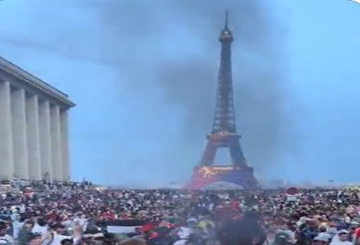
LONDON: France’s unprecedented wave of student protests is highlighting growing pressure on the country’s public finances as the eurozone’s second-largest economy struggles to rein in a widening budget deficit while facing rising demands for public spending.
France’s fiscal position has become increasingly precarious. Public debt exceeded $4 trillion in June, surpassing the size of the economy, according to the country’s statistics agency. The cost of servicing that debt has also risen sharply from last year as government bond yields climb.
At the same time, pressure on the government budget is increasing. Pension spending has risen as France’s population ages, while authorities are also seeking to increase defense expenditure amid heightened security concerns across Europe.
The financial strain has coincided with growing demands from students and the wider public for greater investment in education. High school students have called for action over staff shortages, overcrowded classrooms and deteriorating school infrastructure.
France has repeatedly faced social unrest when governments have attempted to address its fiscal pressures. In 2023, efforts by President Emmanuel Macron’s government to raise the retirement age triggered nationwide protests and strikes.
The latest concerns have intensified after the French government last week proposed spending cuts and tax increases aimed at reducing the budget deficit. However, investors remain concerned that lawmakers could dilute the measures ahead of next year’s presidential election.
Andrew Kenningham, chief European economist at Capital Economics, said investors were likely to remain cautious over France’s fiscal outlook as political pressure builds ahead of the election.
He warned that financial markets could face greater uncertainty if fiscal discipline weakens after the vote, adding that the gap between French and German borrowing costs could widen further.
Bond market pressure
Concerns over France’s debt sustainability intensified last week, triggering a selloff in French government bonds and pushing yields sharply higher.
The spread between French and German government bond yields widened to its highest level since 2012, reflecting investors’ demand for greater compensation to hold French debt compared with German bonds, which are generally viewed as a safer asset.
The turmoil has also raised concerns about possible spillovers into other heavily indebted European economies, reviving memories of the eurozone debt crisis of the early 2010s.
Angel Talavera, chief European economist at Oxford Economics, said France’s economic size and importance to the eurozone meant that financial stress could potentially spread to other countries.
Market concerns also weighed on the euro, which fell to its weakest level against the U.S. dollar since May 2025 on Monday. The currency briefly slipped below $1.12.
Risks extend beyond France
The market turbulence comes as Europe’s economy shows signs of a fragile recovery. Recent activity has been supported by investment in artificial intelligence, stronger demand for European exports and increased defense spending in Germany.
Survey data indicated that economic activity across the euro area’s manufacturing and services sectors accelerated last month at its fastest pace in almost three and a half years.
Economists at Morgan Stanley said Europe’s economy had shown resilience and that growth was beginning to recover.
However, rising government borrowing costs pose a significant risk to that recovery.
Higher bond yields increase borrowing costs across the economy, making mortgages, car loans and corporate financing more expensive while potentially discouraging investment. For governments, higher yields mean greater debt-servicing costs and can increase pressure to cut spending or raise taxes.
Government bond yields in France, Germany and the United Kingdom have recently reached multi-year highs as investors assess whether European governments can maintain their current levels of borrowing.
Jack Allen-Reynolds, deputy chief eurozone economist at Capital Economics, said the region’s public finances posed significant risks to financial markets and the broader European economy.
For France, the challenge is particularly acute: the government must attempt to reduce its deficit and reassure investors while responding to demands for greater spending on pensions, education and defense. How successfully it balances those competing pressures could have consequences well beyond France’s borders.
